What you need to know
- First establish a qualifying compensation event, then reconcile commitments, quantities, use and credits.
- Notify promptly under the contractual procedure; check clause 61.3 and its exceptions.
- A net materials-loss calculation is not automatically an addition to the Prices. Avoid double counting.
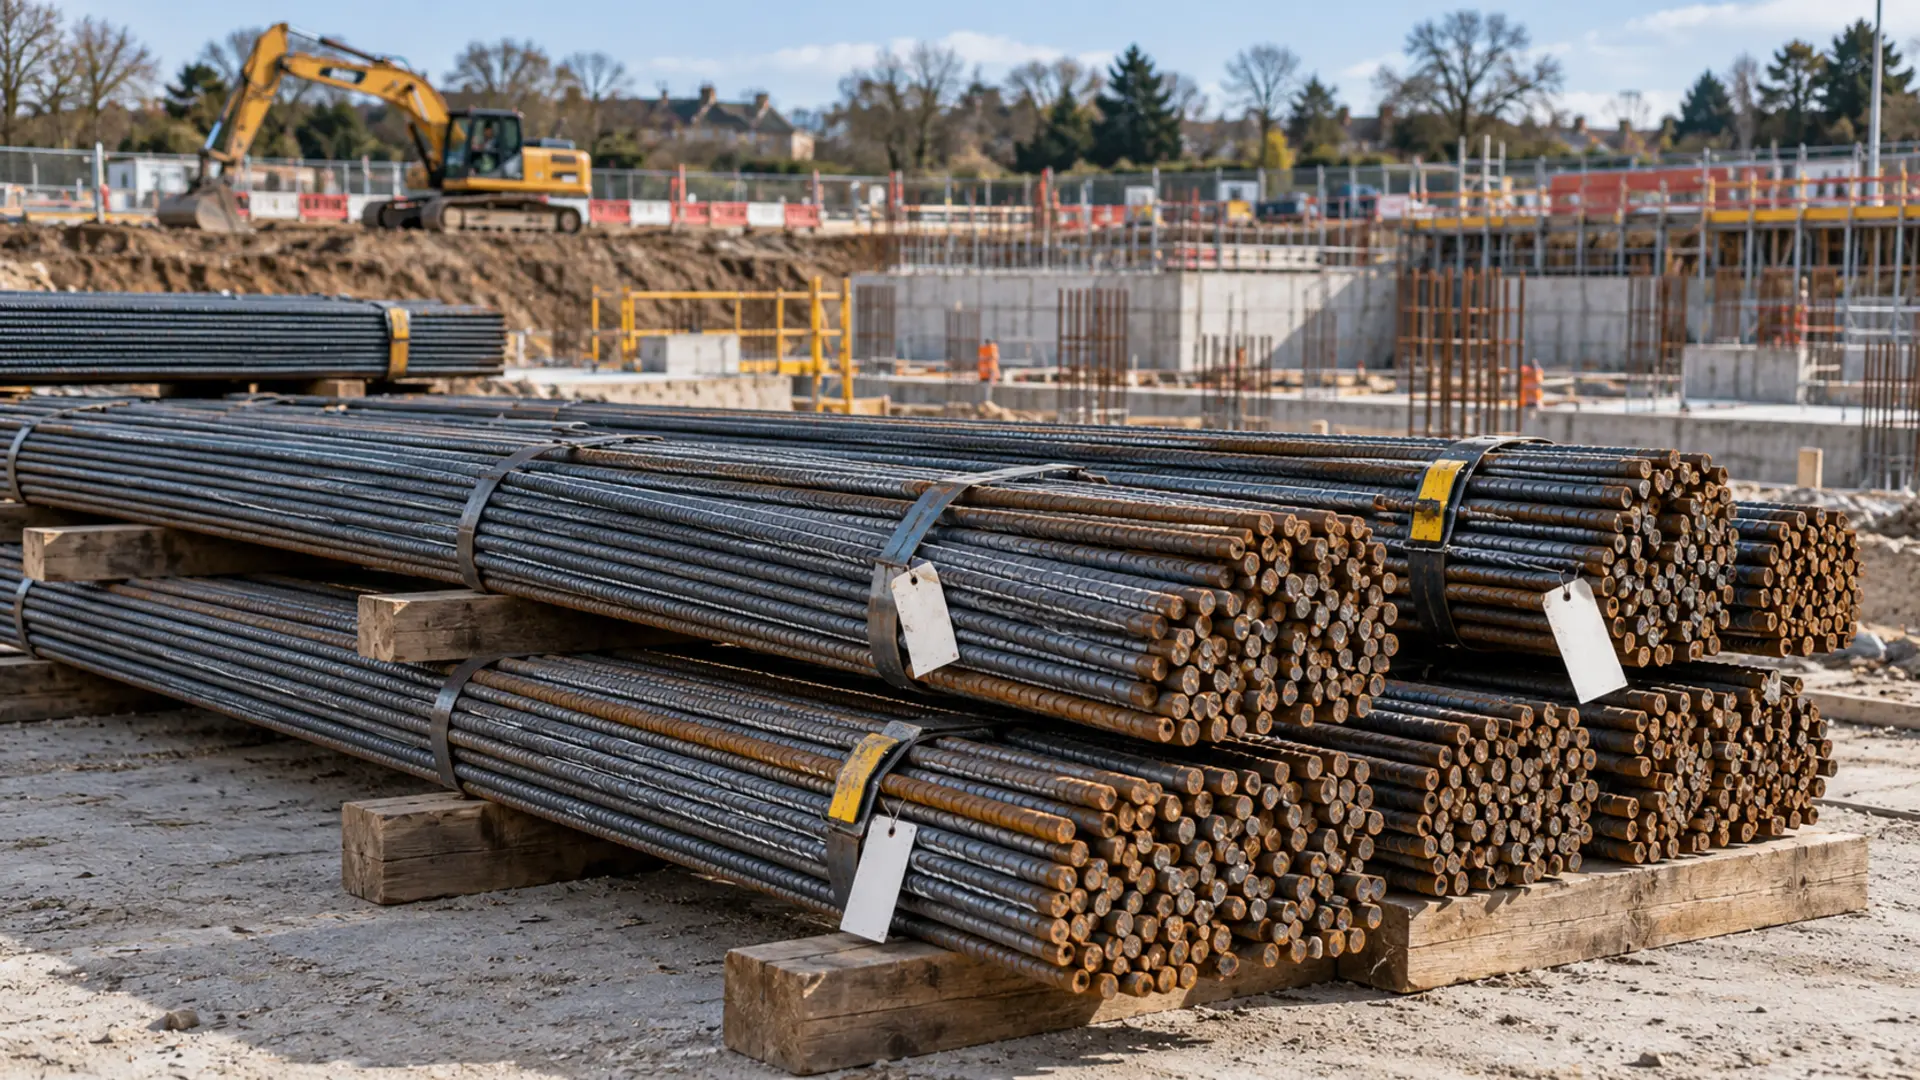
The rebar for the old pile cap design is already on site. Forty tonnes of it, cut and bent. Six tonnes are fixed. The other 34 are stacked in the laydown area.
Then the Project Manager instructs a change to the Client’s design in the Scope. In this illustration it is a qualifying compensation event, rather than a change to correct a Contractor defect or another excluded change. The revised design needs a different bending schedule, leaving the unused bar unsuitable for its original purpose.
The commercial question is what additional cost the event causes and what the records support. Can you show what was ordered, what arrived, what was already used and what value can still be recovered?
Redundant materials can be relevant to a compensation-event assessment, but an invoice for them is not automatically a recoverable addition. Establish the event, its effect, the selected Option and any amendments. Keep the records needed to compare the original position with the changed work.
Three delivery situations that turn into compensation events
1. Materials made redundant by a change
A qualifying instruction changes the Scope under clause 60.1(1) after materials have been ordered or delivered. Not every design revision qualifies: check the stated exceptions and who bears the design responsibility.
Record the original commitment, cancellation or return options, handling and disposal costs, and any credit or reuse value. The assessment must reflect the contract and avoid recovering the same cost twice.
2. Late supply caused by the Client
Late access or another Client-side event may affect a delivery. Identify the particular compensation event and show its effect against the order, programme and actual sequence. A delivery arriving late is not, on its own, a Client-risk event.
3. Extra or different materials for changed work
The changed work needs new materials. You'll forecast or record their cost as part of the assessment. The delivery records show what was bought for the change, as opposed to what was bought for the original work.
Dates decide what you can recover
In each case the question is the same: what happened before the instruction, and what happened because of it?
Separate materials committed before the change, costs caused by the change and costs that would have arisen anyway. Later purchases for an obsolete design may raise questions about competent and prompt reaction under clause 63.9. Record the explanation rather than assuming every unused item is recoverable.
Use order confirmations, drawings, instructions, delivery tickets and stock records together to build the timeline. A delivery date alone does not establish when a cost was committed or why the material became redundant.
The notification clock
Clause 61.3 contains an eight-week notification time bar for certain events, measured from the Contractor becoming aware of the event. Its exception includes events arising from an instruction, notification, certificate or changed earlier decision by the Project Manager or Supervisor. Verify the exact clause and amendments; the trigger is the event, not the date the final materials loss is calculated. Source: NEC notification guidance.
A qualifying Scope-change instruction and a failure to provide access can have different notification treatment. Record the cause and issue the required separate notification through the contract’s procedure. A delivery record or early warning does not replace it.
If the cause or classification is disputed, notify promptly and state the facts. Do not wait until the end of eight weeks or assume that calling a drawing a “clarification” settles entitlement.
How the assessment works
Clause 63.1 assesses the effect on Defined Cost using actual cost for work already done by the dividing date and forecast cost for work not yet done, with the resulting Fee. For a qualifying instruction, the dividing date follows the instruction mechanism. Check the exact wording and the applicable Schedule. Source: GMH dividing-date guidance.
Do not decide actual versus forecast treatment solely from the invoice or payment date. Materials may already have been purchased for work not yet done. Explain the commitment, the work status at the dividing date, the credits and the additional handling or replacement costs; assess each through the contractual rules.
The payment assessment on cost-based Options is a separate check. The unused Plant and Materials limb includes a Scope-change exception, but that does not mean every related cost is automatically allowable or an extra change to the Prices. Apply the relevant definition and avoid duplication with the compensation-event assessment.
When the Project Manager assesses it instead
Clause 64.1 identifies circumstances in which the Project Manager makes an assessment, including failure to submit a quotation within the allowed time and a non-compliant quotation where no revised quotation is instructed. The assessment must follow the contract, not simply what the Project Manager chooses to accept.
A record created at the time remains contemporaneous when found later. The advantage of a linked diary, ticket and quantity record is that it is easier to retrieve and test. Save the originals and record corrections transparently.
Building a materials evidence pack
A complete pack for materials made redundant by an instruction looks like this, using the rebar example. The wider chain behind a materials cost is in delivery notes and Disallowed Cost under NEC4, and the case for capturing tickets at the gate starts with why delivery notes are the most undervalued record on site.
1. The instruction
- Instruction reference and when it was communicated. Check the dividing-date rule rather than treating every internal drawing date as the trigger.
- What it changed, with the before and after drawings.
2. The order
- Purchase order for the original rebar: date raised, supplier, quantity and price.
- The bending schedule the order was placed against.
3. The delivery
- Delivery tickets for each load, dated before the instruction.
- Site diary entries recording each delivery on the day, with the quantity checked and where it was stored.
- Photos of the ticket and the load.
4. The proof it wasn't used
- Progress and stock records showing how much of the original bending schedule was installed, stored, transferred or disposed of.
- A dated photo of the stockpile after the instruction.
- A quantity reconciliation: delivered, used before the instruction, left over.
5. What happened to it
- Supplier correspondence on returns, where the supplier will take material back, with any credit offered.
- Collection or disposal notes, and any scrap credit received.
6. The cost
- Invoices and proof of payment for the original materials.
- Net cost: price paid, less credits, plus handling, removal and disposal.
7. Programme
- Any effect on the Accepted Programme, if the replacement materials had a lead time that pushed the work back.
Build the file as the work happens. Reconstruction later usually takes more effort and may leave gaps; no fixed preparation-time saving is claimed.
A worked materials reconciliation
Illustrative figures only. Forty tonnes of cut-and-bent rebar cost £1,000 per tonne. Six tonnes were fixed before the change, leaving 34 tonnes unsuitable for the original purpose. The table shows a net loss calculation, not the compensation-event value.
Item | Amount |
|---|---|
Redundant rebar paid for: 34t at £1,000 per tonne | £34,000 |
Scrap credit on the redundant bar: 34t at £250 per tonne | minus £8,500 |
Handling, removal and disposal | £2,500 |
Illustrative net loss before Fee and the wider assessment | £28,000 |
The calculation is £34,000 minus £8,500 plus £2,500 = £28,000. It does not mean add £28,000 to the Prices. The quotation must account for the original allowance, work omitted, replacement work, salvage/credits and Fee under the selected Option. If the original materials cost is already included, do not add it again. Keep “40 delivered = 6 used + 34 remaining” separate from the entitlement calculation.
How Gather handles this
Gather records delivery notes within the shift record, alongside the day’s work and resources. Its Record product page also describes photos with timestamps and GPS metadata. These records support a delivery history; they do not, by themselves, confirm the quantity received or prove that materials were used. See the Gather Record product page or book a demo.
FAQ
Can I recover the cost of materials made redundant by a change?
Potentially. First establish a qualifying event and assess its effect under the contract. Show commitments, quantities, unused stock, reasonable response and credits. Recovery and changes to the Prices differ by Option and amendment; no blanket entitlement is claimed.
Does the eight-week time bar apply to redundant materials?
Check the cause of the event. Clause 61.3’s exception can cover events arising from Project Manager or Supervisor communications of the stated types. Other events can be time-barred. Notify promptly through the contractual procedure and verify the wording. Source: NEC notification guidance.
What if we don't have the delivery tickets?
Supplier duplicates, order confirmations, diary entries, photos and stock records may help. Explain the gap and give a supported reconciliation. Lack of a ticket is neither automatic rejection nor proof of entitlement.
Sources
- NEC: Notifying compensation events and time bars, a fairer approach needed
- GMH Planning: Dividing Date, CECA Bulletin 63
- Contract reference: NEC4 ECC clauses 60–64, selected Option, applicable Schedule and Z clauses. Gather Record product page supports only the product description.